This paper explores ways to map and assess financial and operational interconnectedness in insurance companies. Individual insurance entities within a group or conglomerate are often linked with other entities within the group through financial exposures and receive operational services from them. These linkages may be critical for their financial and operational continuity and may have an impact on the design and choice of the preferred resolution strategy
This paper, which highlights a range of current practices from several jurisdictions, could be relevant for all insurance groups, such as Internationally Active Insurance Groups and other insurance groups eligible for resolution planning.
This practices paper discusses the different sources of resolution funding, including privately funded policyholder protection schemes and standalone resolution funds, and how they interact with each other when both exist. The paper also discusses temporary funding sources for resolution funds and mechanisms in place to recover funds used in resolution.
This paper is relevant for supervisory authorities or resolution authorities of any insurer that could be systemic or critical if it fails. Policy makers and resolution authorities may use the Paper as a reference as they develop their resolution funding framework for insurance companies.
Virtual discussion on 10 years of the FSB Key Attributes of Effective Resolution
4 January 2022
On Tuesday 7 December, the Financial Stability Board (FSB) and the Financial Stability Institute (FSI) of the Bank for International Settlements (BIS) hosted a virtual event to assess the achievements of the FSB’s Key Attributes of Effective Resolution Regimes for Financial Institutions, 10 years on.
The Key Attributes were adopted by the FSB in October 2011 as part of the package of policy measures developed following the Global Financial Crisis to address the problem of financial institutions that are “too big to fail”.
The current and former chairs of the FSB Resolution Steering Group – Jelena McWilliams, Mark Branson, Elke König, and Paul Tucker – will discuss the progress made towards ensuring that systemic firms can be resolved in an orderly manner without loss to taxpayers and the challenges that remain. The event will open with a keynote address by Klaas Knot, incoming Chair of the FSB and President of De Netherlandsche Bank.
Call for papers: Systemic risks in non-bank financial intermediation (NBFI) and policies to address them
The Financial Stability Board invites submissions of papers for a conference on systemic risks in non-bank financial intermediation (NBFI) and policies to address them.
The conference, which will take place in June 2022, will contribute to the FSB’s work to develop a systemic approach to NBFI. It will feature presentations of analytical work and research that advances the understanding of systemic risks in NBFI and specific policies and approaches that may be used to address them.
Key areas of interest include:
How to measure interconnectedness (and the potential for the propagation of market stress) within the NBFI sector as well as with banks and the real economy;
The drivers of liquidity imbalances in bond markets (demand and supply sides) and their implications for systemic risk;
Data and analytical tools to enhance NBFI risk assessment and monitoring, including tools to analyse the behaviour of complex systems (e.g. network theory);
The effects and policy implications of the extraordinary interventions by central banks and other authorities to stabilise financial markets during the March 2020 turmoil; and
Policy tools and approaches that can be used by non-bank financial institutions and regulatory authorities to address systemic risk.
The Financial Stability Board (FSB) today published the Global Monitoring Report on Non-Bank Financial Intermediation 2021. The report presents the results of the FSB’s annual monitoring exercise to assess global trends and risks in non-bank financial intermediation (NBFI).
This report presents NBFI developments up to end-2020, the first year of the COVID-19 pandemic, covering 29 jurisdictions that account for approximately 80% of global GDP. The FSB focuses in the report particularly on those parts of NBFI that may pose bank-like financial stability risks and/or regulatory arbitrage (the so-called narrow measure of NBFI).
The main findings from this year’s monitoring exercise include:
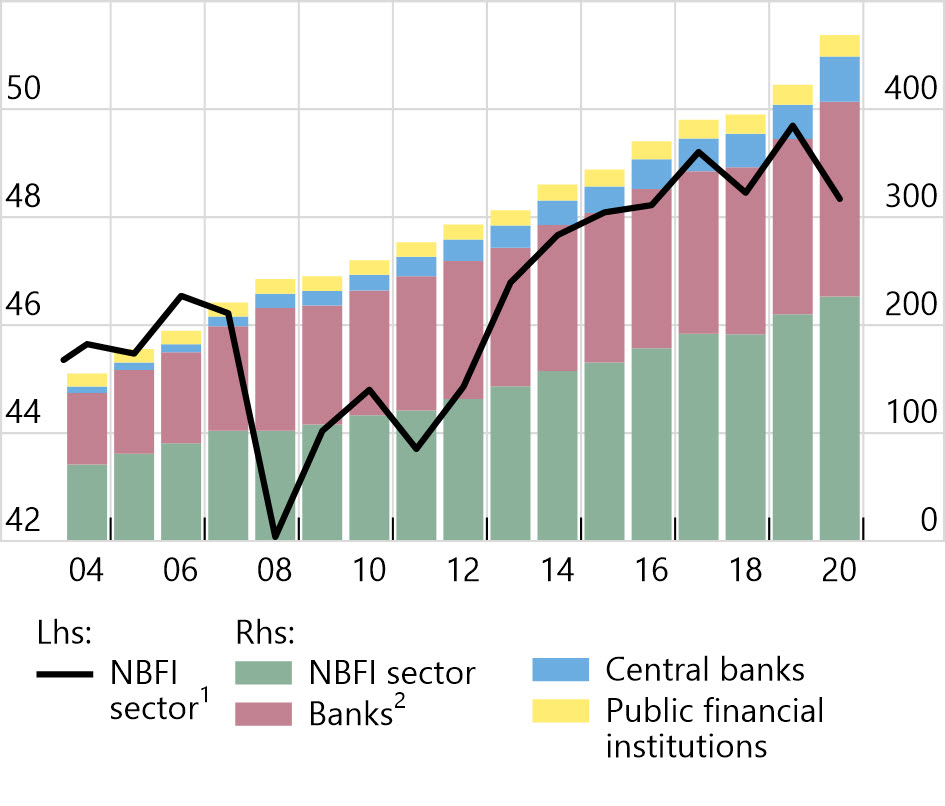
Total global financial assets exhibited strong growth in 2020, increasing by 10.9% to $468.7 trillion. This was mainly driven by banks and central banks, which grew at their highest rate since the 2008 global financial crisis. In contrast to the trend over the past decade, the NBFI sector grew less (7.9%) than the banking sector (11.1%) in 2020.The sector’s share of total financial assets declined from 49.7% in 2019 to 48.3% in 2020.
The narrow measure of NBFI grew by 7.4% in 2020 to $63.2 trillion, broadly in line with its annual growth rate of 7.3% between 2014 and 2019. This growth was driven mainly by collective investment vehicles with features that make them susceptible to runs, which grew by 9.0% in 2020, remaining by far the largest component of the narrow measure (75.1%). As a share of total global financial assets, the narrow measure decreased slightly from 14.1% in 2019 to 13.7% in 2020.
Despite the substantial volatility in financial markets during the first half of 2020, measures of vulnerability in NBFI appeared broadly stable when comparing 2020 to 2019. Largely unchanged measures of credit intermediation, maturity and liquidity transformation and leverage highlight the rapid response and impact of official sector intervention in the wake of the March 2020 market turmoil.
As part of its work programme to enhance the resilience of the NBFI sector, the FSB will consider further enhancements to the annual monitoring exercise in light of the COVID-19 experience.
Notes to editors
The FSB created a system-wide monitoring framework to track developments in NBFI in response to a G20 Leaders’ request at the Seoul Summit in 2010. The objective of the monitoring exercise is to identify the build-up of vulnerabilities in NBFI and initiate corrective actions where necessary. Complementing this monitoring, the FSB has been coordinating the development of policies to mitigate potential vulnerabilities associated with NBFI.
In November 2020, the FSB published a Holistic Review of the March Market Turmoil, which lays out a comprehensive and ambitious work programme for strengthening the resilience of the NBFI sector while preserving its benefits. This work is being carried out within the FSB as well as by its member standard-setting bodies and international organisations, to ensure that relevant experiences and perspectives are brought to bear. The FSB published, in November 2021, a report describing the progress and planned work under its NBFI work programme.
The FSB coordinates at the international level the work of national financial authorities and international standard-setting bodies and develops and promotes the implementation of effective regulatory, supervisory, and other financial sector policies in the interest of financial stability. It brings together national authorities responsible for financial stability in 24 countries and jurisdictions, international financial institutions, sector-specific international groupings of regulators and supervisors, and committees of central bank experts. The FSB also conducts outreach with approximately 70 other jurisdictions through its six Regional Consultative Groups.
The FSB is chaired by Klaas Knot, President of De Nederlandsche Bank. The FSB Secretariat is located in Basel, Switzerland, and hosted by the Bank for International Settlements.
Global Monitoring Report on Non-Bank Financial Intermediation 2021
In contrast to the trend over the past decade, the NBFI sector grew less than the banking sector in 2020.
This report presents the results of the 11th annual FSB monitoring exercise to assess trends and vulnerabilities in NBFI, covering 29 jurisdictions that account for approximately 80% of global GDP.
The report covers NBFI developments for the year ending 31 December 2020, a period that includes both the COVID-19 shock and the extraordinary steps taken by official sector authorities to stabilise financial markets and support financing to the real economy.
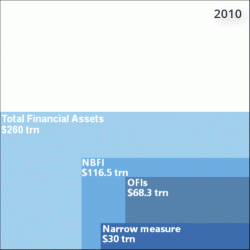
Size of monitoring aggregates and composition of the narrow measure: 2010-2020
Total global financial assets exhibited strong growth in 2020, increasing by 10.9% to $468.7 trillion. This was faster than the global NBFI sector, comprising mainly pension funds, insurance corporations and other financial intermediaries (OFIs)1, which experienced asset growth of 7.9%, reaching $226.6 trillion. The faster growth in bank, central bank, and public financial institution assets than NBFI sector assets is partly attributable to the COVID-19 pandemic, when accommodative official sector responses supported the real economy, including through the banking system.
The NBFI sector’s relative share of total global financial assets therefore decreased from 49.7% to 48.3% in 2020. This was the largest percentage point decrease since the 2008 financial crisis. In particular, asset growth in the NBFI sector was lower than that of central banks (32.3%), and banks (11.1%).
Similar to 2019, NBFI sector growth in 2020 was mainly driven by investment funds, insurance corporations, and pension funds. Growth in investment fund assets was supported by a combination of flows and valuation effects.
Credit intermediation by the NBFI sector increased more slowly than credit intermediation by the banking sector. In 2020, banks’ credit assets grew by 10.5%, a faster pace than credit assets held by insurance corporations (6.4%), pension funds (7.9%) and OFIs (4.6%).
NBFI assets increased in absolute terms, but decreased as a share of total global financial assets
Interconnectedness between banks and the NBFI sector decreased slightly in 2020. Financial interconnectedness is a feature of an open and integrated global financial system. It may help share risk across financial sectors but may also serve as a channel for risk transmission, particularly when entities along intermediation chains employ a high degree of leverage or engage in maturity/liquidity transformation. Therefore, measures of interconnectedness among banks, OFIs, and other non-bank financial entities can serve as important indicators of potential contagion, within and across borders.
The narrow measure of NBFI grew by 7.4% to $63.2 trillion in 2020, at a pace similar to the 2014-19 annual growth rate of 7.3%. At end-2020 it therefore represents 27.9% of total NBFI assets, and 13.7% of total global financial assets. Since the 2008 financial crisis, growth of the narrow measure has been driven primarily by investment funds.
The narrow measure, which reflects an activity-based “economic function” (EF) assessment of risks, includes the following elements:
Collective investment vehicles with features that make them susceptible to runs (EF1) grew by 9.0% in 2020, remaining by far the largest component of the narrow measure with a share of 75.1%. Although investment funds experienced significant outflows in Q1 2020, the prompt recovery in the subsequent two quarters meant they remained the largest contributor to narrow measure growth.
Loan provision that is typically dependent on short-term funding (EF2) grew by 4.2% in 2020, representing 6.7% of the narrow measure. Measures of leverage for finance companies, the entity type most prevalent in EF2, remained stable.
Intermediation of market activities dependent on short-term funding (EF3) grew by 3.7% in 2020, representing 7.8% of the narrow measure. Growth in 2020 was driven, in broadly equal measure, by broker-dealers and custodial accounts, the two main entities classified into EF3.
After strong growth in 2019 (4.5%), insurance or guarantees of financial products (EF4) only grew by 0.4% in 2020. Financial assets associated with these activities still constitute less than 1% of the narrow measure.
Securitisation-based credit intermediation (EF5) shrank by 4.0% in 2020, as assets of Chinese trust companies continued to decrease. EF5 now accounts for 7.5% of the narrow measure.
Assets that are unallocated between the five EFs represent 2.6% of the narrow measure.
Datasets from the report are publicly available for use in accordance with the FSB’s normal terms and conditions.
OFIs include all financial intermediaries that are not central banks, banks, public financial institutions, insurance corporations, pension funds or financial auxiliaries. They include mainly investment funds, captive financial institutions and money lenders, central counterparties, broker-dealers, finance companies, trust companies and structured finance vehicles. [←]
FSB Europe Group discusses non-bank financial intermediation and third-party outsourcing
The Financial Stability Board (FSB) Regional Consultative Group (RCG) for Europe held a virtual meeting today to discuss global and regional financial vulnerabilities and policy initiatives to strengthen financial stability.
The group discussed lessons learnt by financial authorities from COVID-19 and issues arising from recent developments, including those stemming from the rise in indebtedness across sovereigns, non-financial corporates and households and implications for interest rate markets of increases in inflation expectations.
Members discussed the findings to date and next steps under the FSB’s work programme to enhance the resilience of non-bank financial intermediation (NBFI). This includes work by the FSB next year to develop a systemic approach to NBFI by deepening the understanding of associated risks, strengthening their ongoing monitoring and developing policies to address them.
Reliance of financial institutions on digital technology has increased during the pandemic. Against this background, members exchanged views on approaches and challenges in the oversight of financial institutions’ use of third-party service providers, including cloud services.
The group received an update on the FSB’s work programme for 2022, including the planned deliverables to the G20 during the Indonesian Presidency. Members discussed areas of importance for RCG Europe members and how they could contribute to the FSB’s work programme.
Notes to editors
The FSB RCG for Europe is co-chaired by Lowri Khan, Director, Financial Stability at the UK Treasury and Henry Ohlsson, Deputy Governor, Sveriges Riksbank. Membership includes financial authorities from Austria, Belgium, Czech Republic, Denmark, Finland, France, Germany, Greece, Hungary, Iceland, Ireland, Israel, Italy, Luxembourg, Netherlands, Norway, Poland, Portugal, Romania, Spain, Sweden, Switzerland, Ukraine, United Kingdom and the Group of International Finance Centre Supervisors. The European Commission and the European Central Bank also attended the meeting.
The FSB has six Regional Consultative Groups, established under the FSB Charter, to bring together financial authorities from FSB member and non-member countries to exchange views on vulnerabilities affecting financial systems and on initiatives to promote financial stability.1 Typically, each Regional Consultative Group meets twice each year.
The FSB coordinates at the international level the work of national financial authorities and international standard-setting bodies and develops and promotes the implementation of effective regulatory, supervisory, and other financial sector policies in the interest of financial stability. It brings together national authorities responsible for financial stability in 24 countries and jurisdictions, international financial institutions, sector-specific international groupings of regulators and supervisors, and committees of central bank experts. The FSB also conducts outreach with approximately 70 other jurisdictions through its six Regional Consultative Groups.
The FSB is chaired by Klaas Knot, President of De Nederlandsche Bank. The FSB Secretariat is located in Basel, Switzerland, and hosted by the Bank for International Settlements.
The FSB Regional Consultative Groups cover the following regions: Americas, Asia, Commonwealth of Independent States, Europe, Middle East and North Africa, and sub-Saharan Africa. [←]
Guidance on Ways to resolve a financial cooperative while keeping the cooperative structure
As financial cooperatives play an important role in the financial system of a large number of jurisdictions, IADI has developed this guidance paper to analyse ways to resolve a financial cooperative while keeping the cooperative structure, i.e. keeping members, assets and liabilities in the cooperative system.
Although it may be desirable to keep the cooperative structure of a financial cooperative after intervention, this should never be at the expense of financial stability, depositor protection or taxpayer exposure to losses. For this reason, this guidance is directed primarily to the resolution of non-systemic financial cooperatives.
The following main guidance points are provided:
Deposit insurers of financial cooperatives should have in place robust frameworks for early detection and timely intervention, unless such powers are assigned to other institutions or authorities. This increases the chances of keeping the cooperative structure. Also, all deposit insurers should participate in regular contingency planning and simulation exercises.
If deposit insurers co-exist with umbrella organisations or institutional protections schemes, the respective objectives, mandates and powers should be clearly defined in law, regulation or agreements. This could allow for intervention powers by umbrella organisations or institutional protections schemes to enable them to deal with issues faced by a weak FC at an early stage.
In jurisdictions where umbrella organisations or institutional protections schemes can be considered as a first line of defence, deposit insurers with a resolution function and a supervisory function should proactively deal with emerging weaknesses in these organisations. They should have internal contingency plans in place to determine how to deal with such weaknesses. In any case, deposit insurers should have the power to intervene when necessary.
Operationalising bail-in is a critical part of resolution planning for G-SIBs and other firms where bail-in is part of the resolution strategy.
Bail-in is at the core of resolution strategies for global systemically important banks (G-SIBs). The write-down and conversion of Minimum Total Loss-absorbing Capacity (TLAC) instruments, such as bail-in bonds, and other debt into equity helps to facilitate a creditor-financed recapitalisation. It is an important resolution tool set out in the Key Attributes to achieve an orderly resolution that minimises any impact on financial stability and ensures the continuity of critical functions, without exposing taxpayers to loss.
This paper describes some of the main operational processes and arrangements that resolution authorities of G-SIBs follow when operationalising bail-in in accordance with their jurisdictions’ legal frameworks, securities law and requirements of trading venues (TVs).
Drawing on examples and practices across different jurisdictions, this paper provides an overview of bail-in resolution approaches, including the suspension of trading and delisting from TVs of securities of bailed-in firms; the (re-)listing and (re-)admission to trading of new and existing securities as part of the bail-in process.
The paper reviews the role of central securities depositories (CSDs), which play an important role in the execution of bail-in, reflecting bail-in transactions in their books, e.g. the cancellation of shares, write-down and/or conversion of eligible instruments and issuance of new shares and interim instruments.
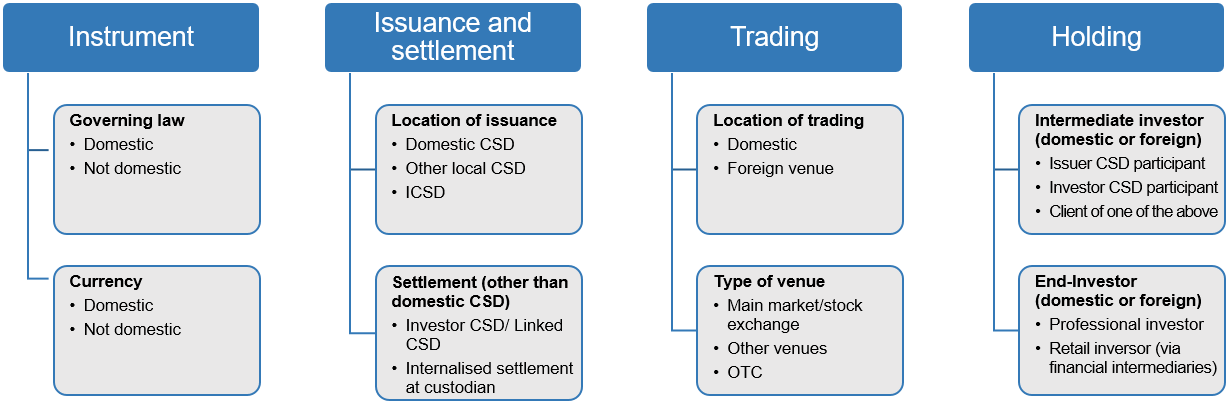
Overview of main Central Security Depository and Trading Venue considerations for bail-in execution
The paper also highlights cross-border challenges to the execution of bail-in, when securities are listed on more than one TV (dual listing or secondary listing) across different jurisdictions, or where securities are issued in a market other than the domestic market. These include the suspension of trading and settlement across all relevant TVs and CSDs; the distribution of the new securities in foreign markets/ to foreign investors; and operational challenges arising for example from the involvement of multiple CSDs. These issues introduce additional complexities to the execution of bail-in, which may need to be specifically addressed as part of resolution planning.
The FSB will continue to facilitate the sharing of practices amongst authorities and efforts to address these issues, including by continuing its engagement with stakeholders as part of the work of its Resolution Steering Group and Bank Cross-Border Crisis Management Working Group.
FSB illustrates practical approaches to the execution of bail-in
Bail-in is at the core of resolution strategies for global systemically important banks (G-SIBs). Set out in the Key Attributes of Effective Resolution Regimes for Financial Institutions, it is an important tool enabling an orderly resolution that minimises any impact on financial stability and ensures the continuity of critical functions, without exposing taxpayers to loss.
Operationalising bail-in is a critical part of resolution planning for G-SIBs and other firms where bail-in is part of the resolution strategy. Since the adoption of the FSB’s Principles on Bail-in Execution, resolution planning has progressed, and authorities have developed approaches and practices in accordance with their respective jurisdictions’ legal frameworks, securities law and exchange requirements.
Drawing on examples and practices across different jurisdictions, this paper provides an overview of practices, operational processes and arrangements as part of the bail-in process. This includes the suspension of trading and delisting from trading venues of securities of bailed-in firms; the (re-)listing and (re-)admission to trading of new and existing securities; and the role central securities depositories (CSDs) play in the cancellation of shares, write-down and/or conversion of eligible instruments, and issuance of new shares and interim instruments.
The paper also highlights cross-border challenges to the execution of bail-in, where securities are listed on more than one trading venue across different jurisdictions, or where securities are issued in a market other than the domestic market. These include the suspension of trading and settlement across all relevant trading venues and CSDs; the distribution of the new securities in foreign markets or to foreign investors; and operational challenges arising for example from the involvement of multiple CSDs. These issues introduce additional complexities to the execution of bail-in, which may need to be specifically addressed as part of resolution planning.
The FSB will continue to facilitate the sharing of practices amongst authorities and efforts to address these issues, including by continuing its engagement with stakeholders as part of the work of its Resolution Steering Group and Bank Cross-Border Crisis Management Working Group.
Notes to editors
The FSB coordinates at the international level the work of national financial authorities and international standard-setting bodies and develops and promotes the implementation of effective regulatory, supervisory, and other financial sector policies in the interest of financial stability. It brings together national authorities responsible for financial stability in 24 countries and jurisdictions, international financial institutions, sector-specific international groupings of regulators and supervisors, and committees of central bank experts. The FSB also conducts outreach with approximately 70 other jurisdictions through its six Regional Consultative Groups.
The FSB is chaired by Klaas Knot, President of De Nederlandsche Bank. The FSB Secretariat is located in Basel, Switzerland, and hosted by the Bank for International Settlements.